
Your First Portland Chiro Visit Billed to Car Insurance
When a Portland chiropractor accepts car insurance, the appointment process looks meaningfully different from a routine wellness visit. The intake forms are different, the examination is more thorough, and the documentation standards are set by insurance adjusters — not just clinical preference. Knowing what to expect at each step protects your health and your claim.
This walkthrough covers everything from the phone call through checkout, including the mistakes Portland patients most commonly make on day one that create billing problems weeks later.
Before You Call: What to Have Ready
Gathering the right information before you dial saves time and prevents gaps in your claim file. Have these items in front of you:
- Your auto claim number. Your insurer assigns this when you report the accident. It is not your policy number.
- Your PIP (Personal Injury Protection) policy limits. Oregon requires a minimum of $15,000 in PIP coverage. Knowing your limit tells the office how much treatment is pre-authorized before additional steps are needed.
- Your adjuster’s name and direct phone number. Adjusters at carriers like PEMCO, State Farm, and Farmers each have different documentation preferences. The front desk will want this contact on file.
- The at-fault party’s insurance carrier and policy number, if you have it. Even when your own PIP pays first — which it does under Oregon law — the office needs this for potential third-party billing later.
- The exact accident date and location. Insurers cross-reference treatment dates against police reports. A one-day discrepancy can trigger a coverage review.
- Any ER or urgent care records from the accident, if you were already seen.
If you don’t have all of this yet, call anyway — but flag what’s missing so the office can follow up before your first appointment.
The Phone Call: What the Front Desk Will Ask and Why
The intake questions for an auto injury case go beyond name and date of birth. Expect the front desk to ask:
How did the accident happen? This isn’t small talk. The mechanism of injury — rear-end collision, T-bone, rollover — determines which body regions the chiropractor will prioritize during examination. It also affects how the clinical narrative is written for the insurer.
Which insurance is paying? Oregon PIP pays first regardless of fault, so the office will open a PIP file under your own policy. They still need the at-fault carrier’s information because once PIP is exhausted, billing shifts to the liability insurer — or to a medical lien arrangement if a personal injury attorney is involved. Offices that regularly work with Portland auto accident insurance billing understand this sequencing and will set up the file correctly from the start.
Have you hired an attorney? If yes, the office may coordinate billing through a letter of protection (LOP), which means treatment costs are paid from any settlement rather than billed to insurance upfront. The front desk needs to know this on day one to structure the file correctly.
Are you currently treating anywhere else? Insurers flag duplicate billing across providers. Disclosing concurrent care protects you and the office.
Arriving at Your First Appointment: The Paperwork That Protects Your Claim
Plan to arrive 15–20 minutes early. Auto injury intake packets are longer than standard new-patient forms, and rushing through them creates problems.
You will typically complete:
- Auto injury intake form. This documents every body part affected, symptom onset, and how symptoms have changed since the accident. Every region you list here can be treated and billed. Regions you omit may not be covered later, even if they worsen.
- HIPAA authorization specific to the claim. This allows the office to release records to your insurer, adjuster, and — if applicable — your attorney. A general HIPAA form is not sufficient for insurance purposes.
- Medical history form. Prior injuries to the same body regions are legally relevant. Oregon adjusters routinely request prior medical records to distinguish pre-existing conditions from accident-related injuries. Disclosing prior issues honestly is always better than having an adjuster discover them later.
- Assignment of benefits form. This authorizes the office to bill your insurer directly so you don’t have to pay out of pocket and seek reimbursement yourself.
Under Oregon PIP, there are no upfront costs to the patient when the office accepts PIP assignment — which is standard practice at chiropractic offices experienced in Oregon PIP chiropractic billing.
The Examination: Why It Differs From a Routine Visit
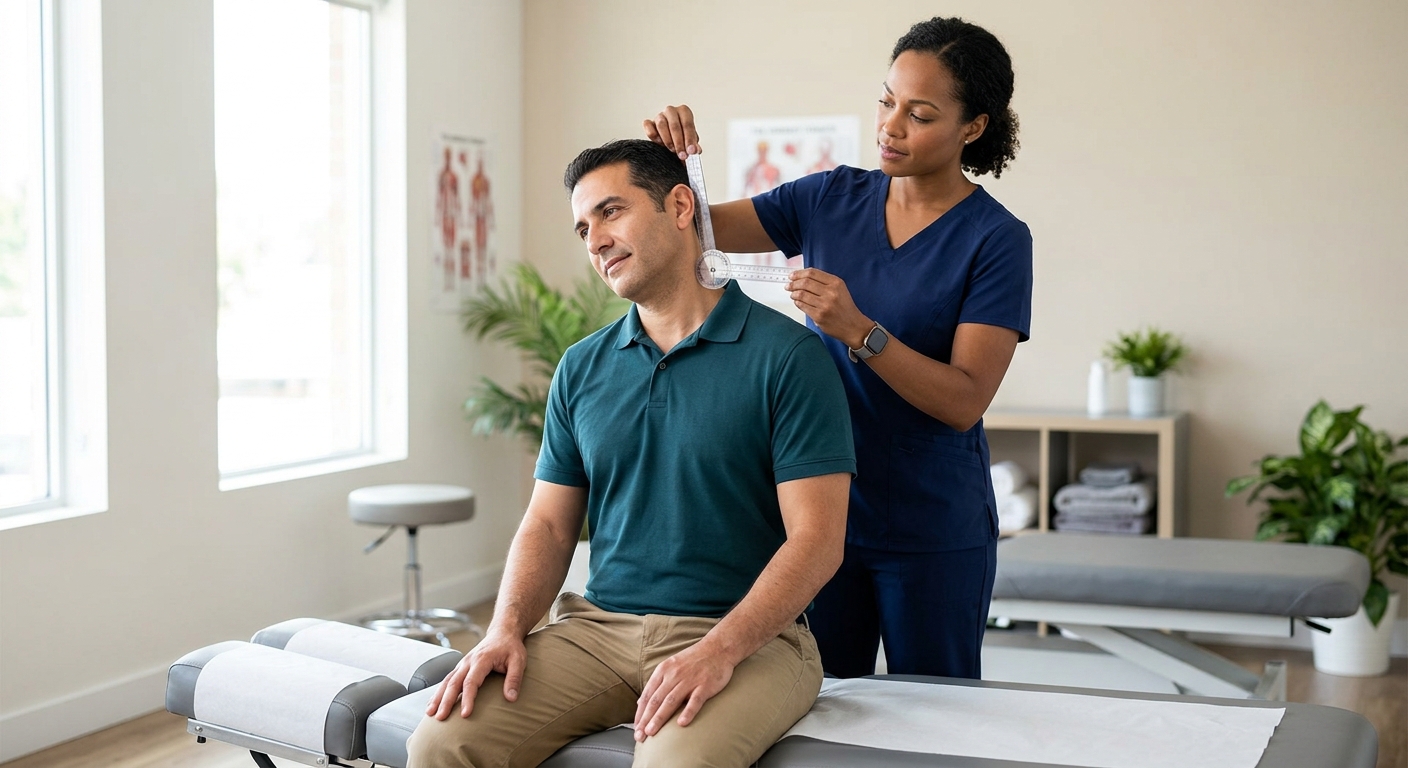
A post-accident chiropractic examination is substantially more detailed than a standard new-patient visit. This is not about thoroughness for its own sake — it is about creating a clinical record that satisfies insurer documentation requirements.
Expect the chiropractor to perform:
Orthopedic testing. Tests like Spurling’s (for cervical nerve compression), Kemp’s (for lumbar involvement), and straight-leg raise assess specific injury patterns. Each test result is documented with a positive or negative finding and clinical interpretation.
Range-of-motion measurements. Using a goniometer or inclinometer, the chiropractor records how far you can move each affected region compared to normal values. These baseline measurements are critical — they establish the starting point against which your recovery is measured, and they are required by most Oregon auto insurers to authorize ongoing care.
Neurological screening. Reflexes, sensation, and muscle strength are tested if nerve involvement is suspected. Findings here can trigger referral for imaging.
Narrative clinical notes. Unlike a SOAP note for a routine adjustment, post-accident notes include a mechanism-of-injury description, functional limitations, and a treatment plan with a projected duration and frequency. Carriers like Farmers and State Farm require this level of documentation before authorizing more than a few visits.
If you are wondering what types of injuries this examination commonly uncovers, the breakdown of what Portland doctors check after a crash covers the clinical findings in detail.
Common Mistakes Portland Patients Make at the First Visit
These errors show up repeatedly and they are all avoidable:
Downplaying symptoms to seem tough. Adjusters assess claim value based on documented injury severity. If you describe a neck injury as “just a little stiff,” that language ends up in the clinical notes and the insurer’s file. Describe your symptoms accurately, including their impact on sleep, work, and daily activities.
Forgetting to mention every affected body part. Patients often focus on their worst symptom and forget to mention secondary areas — a sore shoulder, jaw tension, or lower back ache. If a body part isn’t documented at the first visit, adding it later raises red flags with adjusters who may argue it is unrelated to the accident.
Skipping or rushing the intake forms. Leaving fields blank forces the front desk to make assumptions or follow up later. Incomplete intake documentation is one of the most common reasons insurers request additional records before authorizing treatment.
Not disclosing prior injuries. Attempting to hide a previous neck injury or prior chiropractic care almost always backfires. Adjusters request medical histories routinely. Honest disclosure, combined with a clear clinical explanation of how the accident aggravated a prior condition, is far more defensible than an apparent omission.
Assuming the office will handle everything without your input. The office manages billing, but you are responsible for keeping your adjuster updated on your treatment status. Adjusters who stop hearing from claimants sometimes close files prematurely.
After You Leave: Billing, Authorizations, and What to Do If Problems Arise
After your first appointment, the office submits a CMS-1500 claim form to your PIP carrier. This form includes the diagnosis codes (ICD-10), procedure codes (CPT), and the clinical documentation from your exam. Oregon PIP carriers are required to acknowledge claims promptly, but authorization for ongoing care — typically issued in blocks of visits — may take several days.
If you receive a bill at home before your claim is resolved, do not ignore it and do not pay it out of pocket without calling the office first. Bills sent to patients during an active PIP claim are often generated automatically by billing software and do not reflect that insurance is pending. The office can issue a corrected statement or place the account on hold while the claim processes.
If you receive a denial letter from your insurer, bring it to the office immediately. Denials are often issued for technical reasons — a missing form, a coding question — rather than a substantive coverage dispute. Experienced chiropractic offices can respond to most denials with a corrected submission or supporting documentation.
At Premier Care Chiropractic, we have worked directly with Oregon PIP adjusters at carriers including PEMCO, Farmers, and State Farm for nearly a decade. We structure first-visit documentation specifically to meet adjuster requirements, which reduces authorization delays and keeps your care on track without interruption.